

Sandisk: Fiscal 1Q27 Financial Results
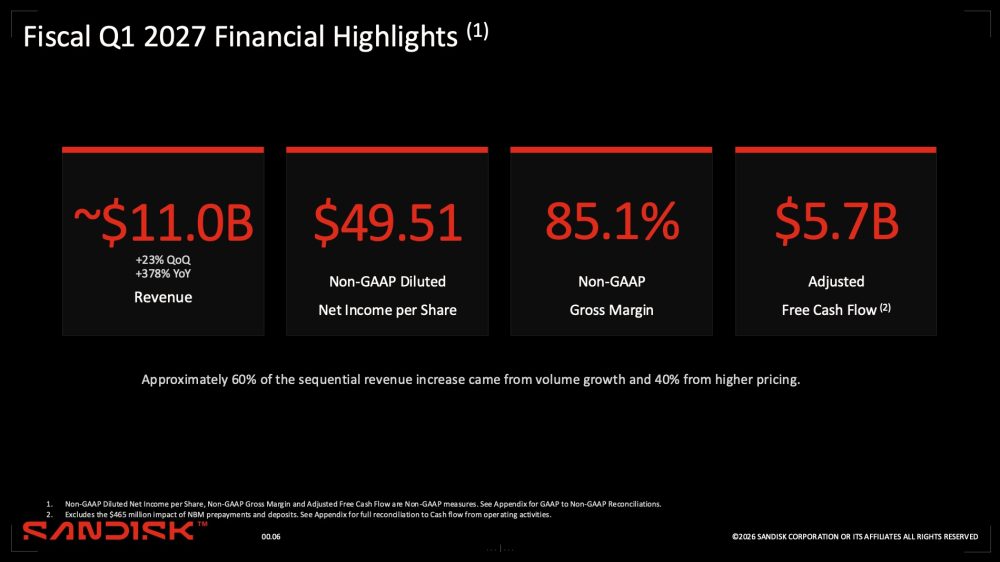
Generating $11 billion, up 23% QoQ and up 378% YoY
This is a Press Release edited by StorageNewsletter.com on November 10, 2026 at 2:02 pmSummary:
- Fiscal first quarter revenue was $11.0 billion, up 23% sequentially, with GAAP net income reported at $8.1 billion ($52.60 diluted net income per share, up 20% sequentially). First quarter Non-GAAP diluted net income per share was $49.51
- Returned $5.0 billion to stockholders through the repurchase of approximately 3.2 million shares during the quarter. Over the past two fiscal quarters, repurchased 6.0 million shares, representing approximately 4% of total shares outstanding
- Announced today an eight-for-one forward stock split, effective November 19, 2026, to make stock more accessible, including to employees through its employee stock purchase plan
- Expect second quarter 2027 revenue to be in the range of $12.2 billion to $12.6 billion, with expected Non-GAAP diluted net income per share on a pre-split basis in the range of $55.00 to $57.001
Sandisk Corp. reported fiscal first quarter financial results. “We have started fiscal year 2027 with another quarter of strong performance, with robust and growing demand for our products driving outpaced growth in our data center business,” said David Goeckeler, chairman and CEO, Sandisk. “We are executing on the strategy that we outlined at Investor Day, delivering growing and durable free cash flow through our technology leadership, deep customer partnerships, and disciplined financial management.”
Sandisk also announced an eight-for-one forward stock split of its common stock to make the stock more accessible, including to employees. The stock split will be effected through an amendment to Sandisk’s Amended and Restated Certificate of Incorporation. Each of the Company’s stockholders of record as of the close of business on November 9, 2026 will receive seven additional shares for each share held, which will be issued after market close on Thursday, November 19, 2026. Trading is expected to begin on a post-split adjusted basis at the market open on Friday, November 20, 2026. Sandisk’s overall market capitalization and stockholder ownership percentages will not be affected by the stock split.
1 All per-share information and metrics in this earnings release are presented on a pre-split basis and do not reflect the recently announced 8-for-1 stock split.
Click to enlarge
Click to enlarge
Comments
Sandisk delivered spectacular numbers for its 1Q27 reaching $11B up 23% QoQ and 378% YoY, this is just amazing and pretty well aligned with other semiconductor players in memory and/or storage sector's numbers like SK hynix, Micron, Kioxia, Solidigm and Samsung to name a few.
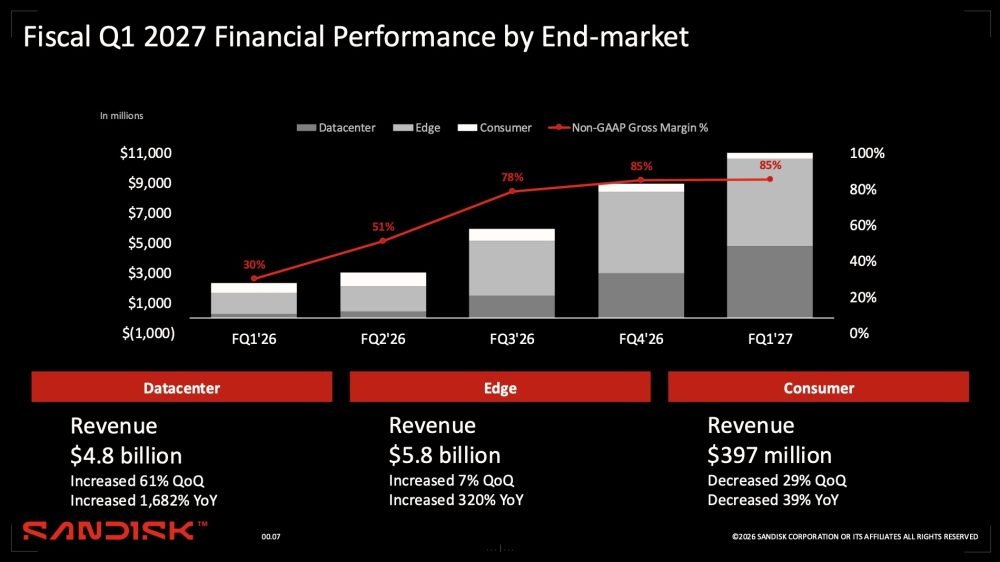
Gross margin at 85% is incredible as well giving the feeling of some market control and manipuation by these players.
Revenue by end-market is also interesting with $4.8B for the datacenter segment (+61% QoQ), edge $5.8B (+7%), consumer $397M (-29%), clearly behind. Datacenter is now about 44% of revenue, versus 12% a year ago. It confirms that AI and associated needed DC infrastructure really push the business.
We also realize that roughly 60% of the sequential increase came from volume and about 40% from pricing. In 4Q26 the split was the reverse, approximately one-third volume, two-thirds pricing.
The projections are so good that they translate about half of FY27 bits and about two-thirds of FY28 bits are committed. The next quarter continues on this trend surfing on new technologies and coming products such as the first High Bandwidth Flash (HBF) die, with samples due in CY27. BiCS10 brings 2Tb QLC.
No surprise but a confirmation we continue to say, this is valid for all similar players, that AI is the engine of the growth. AI inference drove enterprise SSDs to 48% of global NAND shipments in 2Q26, nearly double the 26% a year earlier. Sandisk expects datacenter bit demand to grow about 40% in CY27 and sees KV cache as a structural new workload for NAND.
On the pricing side, based on observation and fine tracking, we estimate that a plateau should appear by end of 2027 or early 2028.
The competition is very hot and Micron is probably the most active competitor, Samsung being the leader with YMTC seen as a coming disruptor. SK hynix has a double face being a rival through Solidigm and a partner with the HBF inititiave.
Like a few other players, Sandisk has muted from a cyclical NAND supplier into a contract-backed AI datacenter model fueled by AI projects poping up everywhere. We'll monitor carefully how YMTC will react and scale but also the consumer demand.


 Subscribe to our free daily newsletter